Run the numbers before you
fall in love with a house.
Our suite of three precision calculators delivers the clarity you need to move forward with absolute confidence. No guesswork, just authoritative answers.
Three questions, three answers
Explore our legacy tools to gain precise, institutional-grade insights into your home financing journey.
Affordability
Determine exactly how much home fits comfortably within your financial landscape, based on current income and market rates.
Rent vs. Buy
Compare the long-term equity growth of homeownership against the financial flexibility of your current lease agreement.
Refinance Savings
Analyze potential monthly savings and lifetime cost reductions by adjusting your current mortgage term or rate.
Your numbers
Adjust anything. The results update as you type...
Run the numbers before you talk to a lender
Three calculators that answer the questions buyers and homeowners actually ask: what can I afford, is buying better than renting, and does refinancing pay off.
Estimates only. Lender approval depends on credit score, loan program, reserves, and how your income documents. Property tax and insurance vary by address.
Assumes the renter invests the down payment, closing costs, and any monthly savings at the return you set. Ignores income taxes, the mortgage interest deduction, and capital gains on investments — all of which shift the result in your specific situation.
Compares principal and interest only; taxes and insurance don't change with a refinance. True cost counts every payment made plus whatever you still owe at the end, so a longer term can't hide behind a smaller payment.
Important Disclaimer: The information and results provided by these mortgage tools are for informational and educational purposes only and are estimates based on the information you provide. Results are not a commitment to lend, loan approval, pre-approval, or guarantee of any specific loan amount, interest rate, payment, or loan terms. Actual eligibility, rates, payments, closing costs, and loan terms may vary based on creditworthiness, income, assets, property type, loan program, market conditions, and other underwriting requirements. All loans are subject to application, verification, underwriting, and approval. Additional terms and conditions may apply.
What a calculator can't tell you
Automated tools assume a perfect W-2 income structure. They cannot accurately account for the complexities of self-employment, fluctuating seasonal earnings, or how essential tax write-offs impact your true qualifying income.
They also overlook the structural nuances of your down payment. Whether you are leveraging family gift funds, contingent on selling an existing property, or holding seasoned assets, these details completely change your purchasing power and require a human touch to document properly.
Beyond principal and interest, true home affordability encompasses localized property taxes, shifting insurance premiums, and hidden HOA fees—variables that general calculators chronically underestimate or ignore entirely.
A documented, professional pre-approval replaces assumptions with certainty. It requires a genuine conversation with an expert to structure your mortgage around your actual life and financial goals, rather than an algorithm's guess.
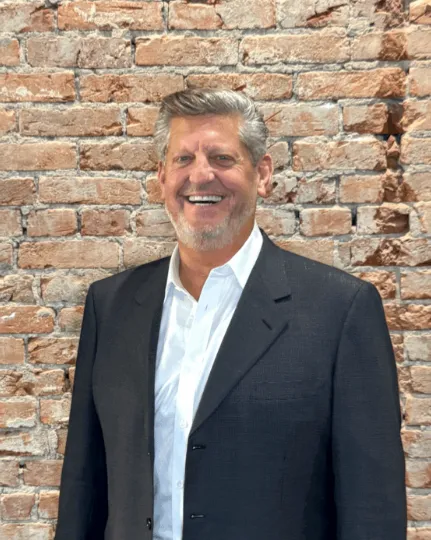
Our Team reads every one
Every tool, calculator, and guide on this platform passes through a rigorous review process to ensure it meets our institutional standards for accuracy and clarity.
We believe that transparency in lending starts with providing you the exact mathematical truth about your mortgage options, without bias or hidden assumptions.
Chris Brown
Owner, Brown A Legacy of Home Lending
Questions People Ask Before They Call
Will using these calculators affect my credit score?
No. Our tools perform soft inquiries or rely entirely on the data you provide. Your credit score remains untouched until you officially apply for a pre-approval.
How accurate are the monthly payment estimates?
Highly accurate. We pull in real-time local tax rates, average insurance premiums, and current interest rates to ensure your estimate reflects what you'll actually pay.
Do I need a 20% down payment to qualify?
Not at all. While 20% eliminates mortgage insurance, many of our loan programs allow for down payments as low as 3%, and some VA or USDA loans require zero down.
What if my credit isn't perfect?
You don't need a perfect score to buy a home. We offer specialized loan options for varying credit profiles. Our team can also guide you on the best steps to improve your standing.
Are closing costs included in these calculations?
Yes, our advanced calculators provide an estimated breakdown of closing costs, so you aren't caught off guard when it's time to finalize your loan.
How soon should I get pre-approved after using the calculators?
Whenever you feel comfortable with your estimated numbers. A pre-approval gives you exact figures and shows sellers you are a serious buyer, putting you in a stronger position.
Ready for a real number?
Our calculations give you a strong estimate, but a verified pre-approval gives you real buying power. Take the next step to lock in your position and shop with confidence.